The Rise of Embedded Finance: Why Everyday Apps Are Becoming Your New Bank
Published • 5 Min Read
Not long ago, managing your money required a distinct destination. You opened a bank’s mobile app to check your balance, visited a lender’s portal to apply for a loan, or accessed a broker's website to purchase stocks.
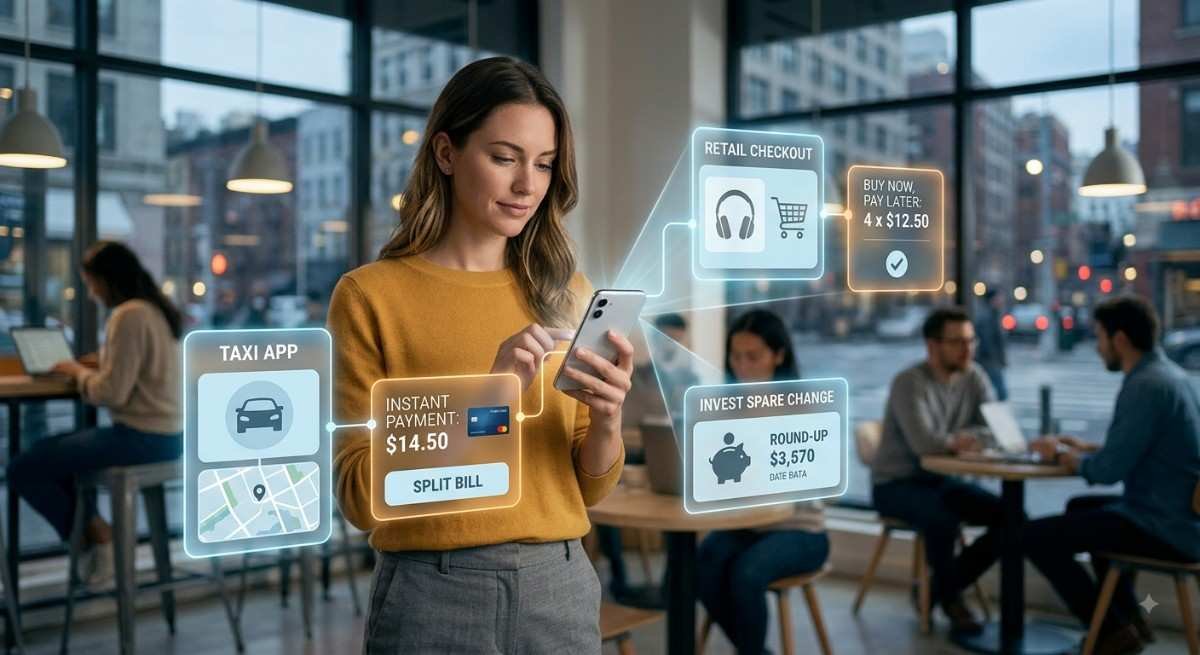
Today, that separation is dissolving. When you split a restaurant bill inside a ride-sharing app, secure travel insurance with a single click while booking a flight, or split a retail purchase into four interest-free payments at checkout, you are participating in embedded finance.
By integrating banking, lending, payment processing, and insurance directly into non-financial digital platforms, everyday software applications are quietly replacing traditional banking touchpoints.
What Is Driven Behind the Shift?
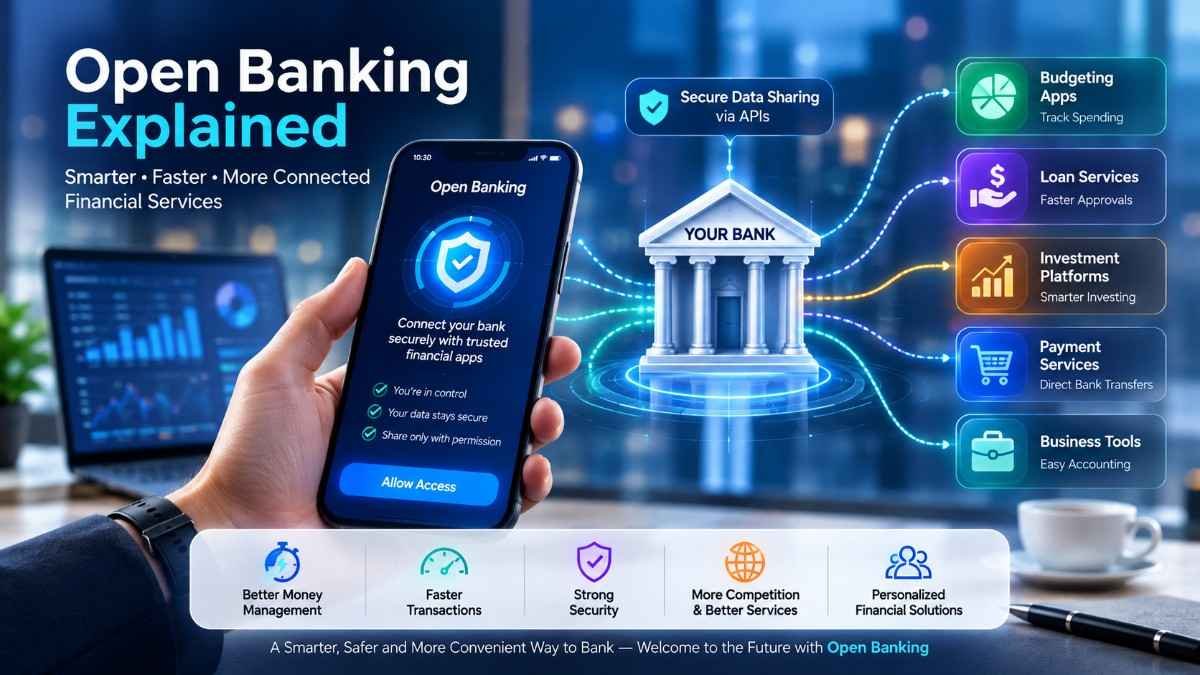
The shift toward embedded finance is enabled by a technology called **Banking-as-a-Service (BaaS)**. BaaS platforms allow regulated financial institutions to license their banking infrastructure via Application Programming Interfaces (APIs).
Instead of building a bank from scratch—which requires navigating complex regulatory frameworks, capital reserves, and legacy back-end systems—a software company can integrate financial services into its existing app with a few lines of code.
Three primary drivers are accelerating this transition:
1. Consumer Expectation for Zero Friction: Modern users expect contextual utility. Redirecting a customer to a third-party payment gateway or asking them to fill out a lengthier bank application creates friction and cart abandonment.
2. Platform Monetization: For software-as-a-service (SaaS) platforms and e-commerce giants, embedding financial products expands revenue per user. Instead of relying solely on subscription fees or transaction charges, platforms capture financial margin, interchange fees, and interest spread.
3. Data Richness: Non-financial platforms often know more about consumer and vendor behavior than traditional banks do. A food delivery app knows a restaurant’s daily cash flow in real-time, making it far safer and faster for the platform to issue a micro-loan than a traditional bank relying on historical tax returns.
The Core Pillars of Embedded Finance
Embedded finance spans virtually every service traditionally offered by retail and commercial banks:
```
┌─────────────────────────────────────────┐
│ EMBEDDED FINANCE ECOSYSTEM │
└────────────────────┬────────────────────┘
│
┌──────────────────┬───────────┴───────────┬──────────────────┐
▼ ▼ ▼ ▼
┌───────────────┐ ┌───────────────┐ ┌───────────────┐ ┌───────────────┐
│ Embedded │ │ Embedded │ │ Embedded │ │ Embedded │
│ Payments │ │ Lending │ │ Insurance │ │ Investments │
└───────┬───────┘ └───────┬───────┘ └───────┬───────┘ └───────┬───────┘
│ │ │ │
In-app wallets, Buy Now Pay Later, Contextual cover Fractional stocks
1-click payment working capital credit at point of sale & auto-roundups
1. Embedded Payments
The most mature segment of embedded finance is invisible payment processing. Apps like Uber or Starbucks store payment credentials to process transactions automatically in the background. Consumers no longer "pay"; they simply complete an action, and the financial settlement happens behind the scenes.
2. Embedded Lending & POS Financing
Buy Now, Pay Later (BNPL) services and point-of-sale working capital loans allow consumers and businesses to access credit at the exact moment of purchase. By analyzing real-time data at checkout, embedded lenders can underwrite loans in seconds, boosting conversion rates for merchants by 20% to 30%.
3. Embedded Insurance
Rather than purchasing an annual insurance policy through an broker, consumers are buying micro-insurance policy add-ons inside transactional workflows—such as device protection during an electronics purchase, or ticket refund coverage on a concert ticketing site.
4. Embedded Investments
Non-financial platforms increasingly allow users to invest spare change or buy fractional shares within everyday apps. From round-up savings features attached to debit cards to gig-economy platforms offering workers automated index-fund contributions, wealth management is becoming a passive, background feature.
B2B Embedded Finance: The Next Big Horizon
While consumer-facing applications capture headlines, the largest immediate growth opportunity lies in **Business-to-Business (B2B) embedded finance**.
Enterprise Resource Planning (ERP) tools, accounting software, and supply-chain platforms are embedding payroll, corporate cards, invoice factoring, and cross-border payments directly into business management dashboards. Rather than waiting 30 to 90 days for client invoices to settle, small businesses can access instant working capital directly inside the software they use to manage inventory.
Strategic Challenges and Outlook
Despite rapid growth, embedded finance faces critical headwinds:
Regulatory Scrutiny:** Regulators globally are tightening oversight on BaaS sponsor banks and tech platforms to ensure risk management, anti-money laundering (AML) compliance, and consumer protections remain intact.
Data Privacy and Security:** As sensitive financial data flows through non-bank software infrastructure, platforms become higher-value targets for cybersecurity threats.
Conclusion
Banks are not disappearing, but their role is shifting from consumer-facing destinations to underlying utility infrastructure. As everyday software platforms continue to weave payments, lending, and wealth management directly into daily routines, the "bank" of the future will simply be the app you open most often.